Bundled AI changes what an eDiscovery contract buys.
The eDiscovery vendor you are using today probably will not exist in its current form in eighteen months. That is not pessimism -- it is the math. In February 2026 alone, HaystackID swallowed eDiscovery AI, DISCO blew up its own pricing model by bundling agentic AI at no extra charge, and Relativity formally killed on-premises sales to push everyone onto RelativityOne. Three structural moves in a single month, against a backdrop of 200+ M&A deals in the sector over the past several years. If your litigation practice depends on eDiscovery technology (which, in 2026, means virtually every litigation practice), you need to understand what is happening and what it means for your technology stack, your budgets, and your competitive position.
The market in motion: three shifts, one quarter
The eDiscovery market is projected to reach $20.74 billion globally in 2026, growing at a compound annual growth rate north of 10%.1 But raw market growth tells only part of the story. The more significant development is how that market is being restructured -- fundamentally reorganizing around new commercial models, ownership structures, and technical architectures.
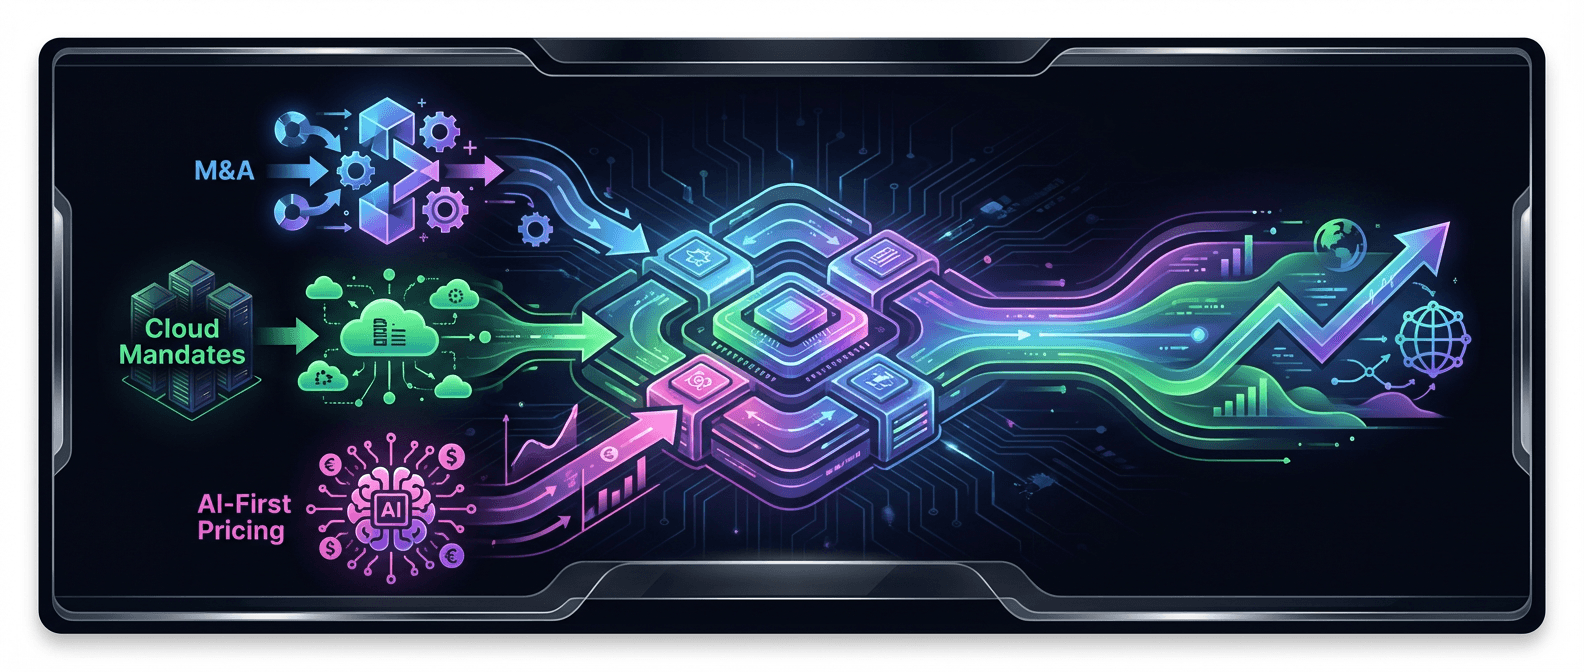
Three developments in February 2026 alone crystallize the trend:
- HaystackID acquired eDiscovery AI, an AI-native legal technology company, to integrate generative AI capabilities across its legal, compliance, and cybersecurity workflows.2
- DISCO launched an all-inclusive platform combining eDiscovery, its Cecilia AI, deposition management, and timelines at a single per-gigabyte price -- with agentic AI included at no additional charge.3
- Relativity confirmed its cloud-only future, formally ending on-premises sales and cementing RelativityOne as the sole path forward for the platform's user base.4
Each of these moves, taken alone, would be significant. Together, they represent a tectonic shift in how eDiscovery technology is built, sold, and consumed. And they're happening against a backdrop of accelerating M&A activity that has seen well over 200 deals in the eDiscovery sector over the past several years.5
Figure 1: Three converging forces remaking eDiscovery vendor economics in 2026.
The HaystackID-eDiscovery AI deal: when service providers acquire AI-native companies
HaystackID's acquisition of eDiscovery AI, announced February 26, 2026, is a textbook example of a pattern we're going to see repeated across the industry: established service providers acquiring AI-native startups to leapfrog their own R&D timelines.
Chad Pinson, HaystackID's CEO, framed the rationale clearly: "Our clients are asking for easy-to-deploy GenAI capabilities that deliver deep insights, defensible results, and adaptability to changing use cases."2 That's not aspirational language -- it's a description of client demand that has moved past evaluation and into operationalization.
What makes this deal particularly instructive is its structure. HaystackID chose a dual-entity operating model: existing eDiscovery AI clients continue to be served through a separate business entity, while HaystackID simultaneously integrates the technology into its own platform offerings. Jim Sullivan remains as CEO of eDiscovery AI, providing leadership continuity.2
This approach acknowledges a practical reality that many acquirers overlook: clients who chose a specialist AI provider did so deliberately, often because they valued independence from larger platform vendors. Forcing immediate integration would risk those relationships. The dual-entity model preserves optionality -- for both the acquirer and the acquired company's clients.
What eDiscovery AI brings to the table
eDiscovery AI's technology specializes in AI-powered data intelligence, document review streamlining, and workflow automation for litigation, investigations, and compliance matters.6 The company had already built integrations with major platforms including Relativity, positioning it as a technology layer that enhances existing workflows rather than replacing them.
Michael Sarlo, HaystackID's Chief Innovation Officer, captured the market moment precisely: "Clients are no longer evaluating GenAI in theory; they are operationalizing it across early case assessment, investigations, regulatory response and review quality controls."2
That phrase (operationalizing, not evaluating) is the key distinction in 2026. The pilot phase is over. What matters now is whether your provider has production-grade AI that meets enterprise governance and security standards.
The broader pattern: build vs. buy in legal AI
HaystackID's acquisition fits a broader industry pattern. When the cost and time required to build competitive AI capabilities internally exceeds the cost of acquiring a company that's already solved the problem, acquisition becomes the rational choice. And with generative AI capabilities advancing on a quarterly release cycle, the build option is increasingly impractical for service providers whose core competency is legal operations, not machine learning engineering.
ComplexDiscovery's tracking of eDiscovery M&A activity shows this isn't isolated. The database documents well over 200 mergers, acquisitions, and investments in the eDiscovery sector since the industry's earliest days, with activity accelerating in recent years.5 The difference in 2026 is the type of acquisition: rather than geographic expansion or client list consolidation, the deals are now explicitly about acquiring AI capabilities.
DISCO's all-inclusive gambit: rewriting the pricing playbook
While HaystackID was acquiring AI capabilities, DISCO was making an equally consequential move on the commercial side of the market. On February 25, 2026, the company announced a complete platform restructuring: an all-inclusive solution combining eDiscovery, Cecilia AI, deposition management (formerly Case Builder), timelines, and a new Auto Review capability -- all at a single, transparent per-gigabyte price on processed data with no ingest fees.3
The headline feature? DISCO's "first-of-its-kind agentic AI solution for eDiscovery" included at no additional charge.3
At a moment when most vendors are figuring out how to monetize their AI features (often through premium tiers, per-query pricing, or add-on modules), DISCO is bundling agentic AI into its base platform price for free.
The strategic calculus
CEO Eric Friedrichsen explained the logic: "Fast-evolving generative AI capabilities are demonstrating that one-off eDiscovery products are increasingly inadequate. DISCO's platform assembles the most impactful tools for modern litigation into a seamless end-to-end solution."3
Chief Product Officer Richard Crum reinforced the positioning: "We're building integrated tools tackling the full litigation lifecycle, not point solutions."3
This is a deliberate competitive strategy aimed at two audiences simultaneously:
- Against incumbent platforms (primarily Relativity): DISCO is arguing that an integrated, all-inclusive platform is superior to an ecosystem model where core capabilities are spread across the platform vendor and a constellation of third-party add-ons.
- Against point solution vendors: By bundling capabilities that many firms currently purchase separately (deposition management, case timelines, AI-assisted review), DISCO eliminates the multi-vendor complexity tax.
The pricing transparency play
The shift to per-gigabyte pricing on processed data with no ingest fees is arguably as significant as the AI bundling. eDiscovery pricing has historically been opaque, with complex fee structures involving hosting fees, per-page charges, processing fees, review tool licensing, and AI add-on costs. This complexity has long been a pain point for litigation teams trying to forecast costs and compare vendors.
| Pricing Model | Traditional eDiscovery | DISCO All-Inclusive |
|---|---|---|
| Data ingestion | Per-GB ingest fee | Included |
| Processing | Per-GB processing fee | Included |
| Hosting | Monthly per-GB fee | Included |
| Review tools | Per-user licensing | Included |
| AI features | Premium add-on tier | Included |
| Depositions | Separate product | Included |
| Timelines | Separate product | Included |
Table 1: Comparison of traditional eDiscovery pricing vs. DISCO's all-inclusive model.
DISCO's move forces competitors to either match the transparency or explain why their pricing complexity is justified. For litigation teams that have struggled with eDiscovery cost predictability, this could be a compelling value proposition.
Figure 2: The three converging market moves of Q1 2026 and their cascading impact on buyer segments across eDiscovery.
Relativity's cloud-only mandate: the end of on-premises eDiscovery
The third pillar of the 2026 consolidation story is Relativity's formal transition to a cloud-only model. The company's decision to end on-premises sales of its technology represents the final chapter of a migration that began years ago with the launch of RelativityOne.4
For an industry where Relativity has long been the dominant platform -- with the largest ecosystem of third-party integrations, the deepest bench of certified professionals, and the most extensive partner network -- this is a watershed moment. Organizations that have maintained on-premises Relativity installations, often for data sovereignty, security, or cost control reasons, now face a mandatory cloud migration timeline.
Why it matters beyond the technology
The cloud-only mandate accelerates several market dynamics:
- Reduced switching costs: Once organizations accept they must migrate, some will evaluate competing cloud platforms rather than defaulting to RelativityOne. Everlaw, which has been cloud-native from inception and currently leads G2's eDiscovery rankings for four consecutive quarters, is the most obvious beneficiary.7
- Ecosystem disruption: Third-party vendors that built on-premises integrations with Relativity's server-based architecture must rebuild for the cloud. This creates an opening for cloud-native competitors.
- Pricing pressure: Cloud-based models shift eDiscovery from capital expenditure to operating expenditure, making total cost of ownership more visible and comparable across vendors.
The ALSP factor: alternative legal service providers as consolidation accelerators
The M&A and platform shifts aren't happening in a vacuum. They're being driven, in part, by the explosive growth of alternative legal service providers (ALSPs), which are capturing an increasing share of litigation technology spend.
The 2026 Legal Market Report places the U.S. ALSP segment at a trajectory from $7.37 billion in 2022 to over $23 billion by 2028 -- a compound annual growth rate of approximately 20.9%. The eDiscovery subset of that market is growing even faster, at roughly 23% annually.8
This growth creates both demand for consolidated platforms (ALSPs want fewer vendors, not more) and acquisition targets (ALSPs with proprietary AI capabilities become attractive to larger players seeking technology differentiation).
The demand redistribution effect
The same report identifies what it calls "mobile demand" -- legal work shifting from Am Law 100 firms to midsize and Second Hundred firms. This redistribution is increasingly driven by "technology leverage, playbooked workflows, and price discipline" rather than firm prestige.8
For eDiscovery vendors, this means the buyer profile is changing. The firms driving growth aren't the largest firms with unlimited technology budgets -- they're midsize firms and corporate legal departments that need powerful, cost-effective, easy-to-deploy solutions. That's precisely the market that all-inclusive, cloud-native platforms are designed to serve.
The in-house revolution: corporate legal teams taking control
Perhaps the most underappreciated force driving eDiscovery consolidation is the rapid AI adoption by corporate legal departments. According to recent industry data, corporate legal AI adoption more than doubled in one year, jumping from 23% to 52%. Even more striking: 64% of in-house teams now expect to depend less on outside counsel because of AI capabilities they're building internally.9
This shift has profound implications for eDiscovery vendors:
- Direct enterprise sales become more important than law firm channel partnerships
- Self-service platforms gain advantage over service-heavy models that assume law firm intermediaries
- Integration with corporate systems (Microsoft 365, Slack, cloud storage) matters more than integration with legal-specific tools
- Predictable pricing is essential for corporate budgeting processes that can't tolerate per-matter variability
The vendors best positioned for this shift are those offering integrated, cloud-native platforms with transparent pricing -- exactly the model DISCO just launched and the direction Relativity's cloud-only mandate pushes the market.
What the consolidation means for litigation teams
For law firms
The consolidation wave creates both risk and opportunity for law firms:
Risk: Firms locked into a single vendor face reduced leverage as that vendor consolidates market power. The acquisition of niche AI providers by larger platforms means fewer independent alternatives.
Opportunity: Firms willing to evaluate and adopt the new all-inclusive models can potentially reduce total cost of ownership, simplify their technology stack, and offer clients more predictable pricing -- which corporate legal departments increasingly demand.
For corporate legal departments
In-house teams are the clearest beneficiaries of the consolidation trend:
- Simplified vendor management: Fewer vendors means fewer contracts, fewer security reviews, and fewer integration headaches
- Cost predictability: All-inclusive pricing models align with corporate budgeting norms
- AI access without premium pricing: Bundled AI capabilities lower the barrier to adoption
- Cloud-native deployment: Eliminates the need for on-premises infrastructure management
For smaller firms and solo practitioners
This is where the consolidation story intersects with access to justice. Historically, the best eDiscovery technology was priced for Am Law 200 firms and Fortune 500 legal departments. All-inclusive pricing models, cloud-native delivery, and bundled AI capabilities have the potential to democratize access to tools that were previously cost-prohibitive for smaller practices.
That potential, however, depends on whether vendors pursue a market expansion strategy (lower prices, broader access) or a margin optimization strategy (higher prices, fewer clients). The trajectory of DISCO's pricing experiment will be instructive.
Figure 3: How the consolidation wave impacts each buyer segment differently, from law firms re-evaluating vendor stacks to smaller practices gaining access to previously cost-prohibitive AI tools.
The GenAI pricing paradox
The consolidation wave is occurring against a backdrop of what the 2026 Legal Market Report calls a fundamental tension: approximately 90% of legal dollars still flow through hourly billing, even as GenAI deployment compresses the hours required to perform key tasks.8
For eDiscovery specifically, this creates a paradox:
- AI-assisted review dramatically reduces the volume of billable review hours
- Vendors need to monetize their AI investment
- Law firms using hourly billing lose revenue when AI makes them more efficient
- Corporate clients expect to capture efficiency gains as cost savings
The vendors navigating this paradox most effectively will be those who align their pricing with outcomes rather than inputs -- charging for processed data volume (DISCO's model) rather than for review hours or AI queries. This shifts the economic incentive toward efficiency rather than against it.
Where the pricing models are heading
| Model | Aligns Incentives? | Predictable? | Current Adoption |
|---|---|---|---|
| Per-GB processed | Yes | High | Growing (DISCO) |
| Per-user licensing | Partially | Medium | Common (Relativity) |
| Per-query AI pricing | No | Low | Emerging |
| Hourly + AI surcharge | No | Low | Common (service firms) |
| All-inclusive bundle | Yes | High | New (DISCO) |
Table 2: eDiscovery pricing model comparison and incentive alignment.
Looking ahead: what comes next
The consolidation dynamics of Q1 2026 are early-stage manifestations of a multi-year restructuring. Over the next 12-18 months, expect the following:
More AI-focused acquisitions
HaystackID's acquisition of eDiscovery AI won't be the last deal of its kind. Every major eDiscovery service provider that lacks proprietary AI capabilities is now a potential acquirer, and every AI-native legal tech startup with production-grade technology is a potential target. The Legalweek 2026 conference, where both HaystackID and eDiscovery AI exhibited just weeks after the deal closed, is likely where the next round of conversations began.2
Platform convergence
DISCO's all-inclusive model will force responses from Relativity, Everlaw, and others. Relativity's ecosystem model, where third-party developers build on the platform, has been its greatest competitive strength. But the all-inclusive trend challenges that model by arguing that integration complexity is a cost, not a feature. Expect Relativity to bundle more capabilities natively and Everlaw to expand its platform scope.
The cloud migration accelerates
With Relativity ending on-premises sales and cloud-based solutions projected to represent 78% of the eDiscovery market by 2029, the remaining on-premises holdouts face increasing pressure.10 Organizations that haven't begun cloud migration planning should start now -- not because the technology demands it, but because the vendor ecosystem is being rebuilt around cloud-native architectures.
Corporate legal departments as kingmakers
The doubling of corporate legal AI adoption is not a blip -- it's a structural shift in who controls eDiscovery technology decisions. Vendors that orient their product development, pricing, and sales models toward enterprise buyers will gain market share. Those that continue to sell primarily through law firm channels risk being disintermediated.9
The view from the ground
I've watched enough technology transitions in this industry to know that vendor announcements and market projections don't always translate to practitioner reality on the timeline the vendors promise. Cloud migrations take longer than expected. AI capabilities oversell and underdeliver. Acquisitions create integration headaches that take years to resolve.
But the structural dynamics of 2026 are different in one critical respect: buyers are driving them. Corporate legal departments are demanding AI capabilities, pricing transparency, and platform consolidation. Midsize firms are choosing technology partners based on total cost of ownership rather than brand prestige. The ALSP sector is growing at 20% annually because clients want technology-leveraged alternatives to traditional law firm delivery models.8
The vendors responding to these demands, whether through acquisition (HaystackID), platform restructuring (DISCO), or cloud mandates (Relativity), are adapting to a market that has fundamentally shifted. The ones that don't adapt will find themselves on the wrong side of the consolidation wave.
For litigation teams evaluating their eDiscovery technology stack in 2026, my advice is straightforward: understand the consolidation dynamics, evaluate the new pricing models on their merits, and don't assume that your current vendor relationship will look the same in 18 months. The market is moving. Make sure you're moving with it.
- 1Fortune Business Insights, "eDiscovery Market Size, Share, Trends | Growth Report [2034]," Fortune Business Insights eDiscovery Report
- 2HaystackID, "HaystackID Acquires eDiscovery AI to Accelerate Client-Driven GenAI Workflows," February 26, 2026, HaystackID Press Release
- 3DISCO, "DISCO Announces All-Inclusive Platform for eDiscovery," February 25, 2026, DISCO Press Release
- 4Everlaw, "The Future of eDiscovery Is in the Cloud," Everlaw Blog
- 5ComplexDiscovery, "eDiscovery Mergers, Acquisitions, and Investments," ComplexDiscovery M&A Tracker
- 6ComplexDiscovery, "HaystackID Acquires eDiscovery AI to Advance GenAI Across Legal, Compliance, and Cyber Workflows," ComplexDiscovery Coverage
- 7Everlaw, "Everlaw vs. Relativity," Everlaw Comparison
- 8ComplexDiscovery, "Fault Lines Under Big Law: What the 2026 Legal Market Report Means for Data-Driven Providers," ComplexDiscovery Analysis
- 9Legal IT Insider, "Unpicking the Legal AI Market: The Forces Reshaping Legal in 2026," March 3, 2026, Legal IT Insider
- 10ComplexDiscovery, "Complete Look: ComplexDiscovery's 2024-2029 eDiscovery Market Size Mashup," ComplexDiscovery Market Size